NRI Estate Planning: 5 Things Parents Must Get Right
Children abroad, assets in India? Why a Will is not enough: executors, trusts, nominations, NRO accounts, inheritance tax and the USD 1 million limit.

Nikhil Varghese, CA · 10 min read
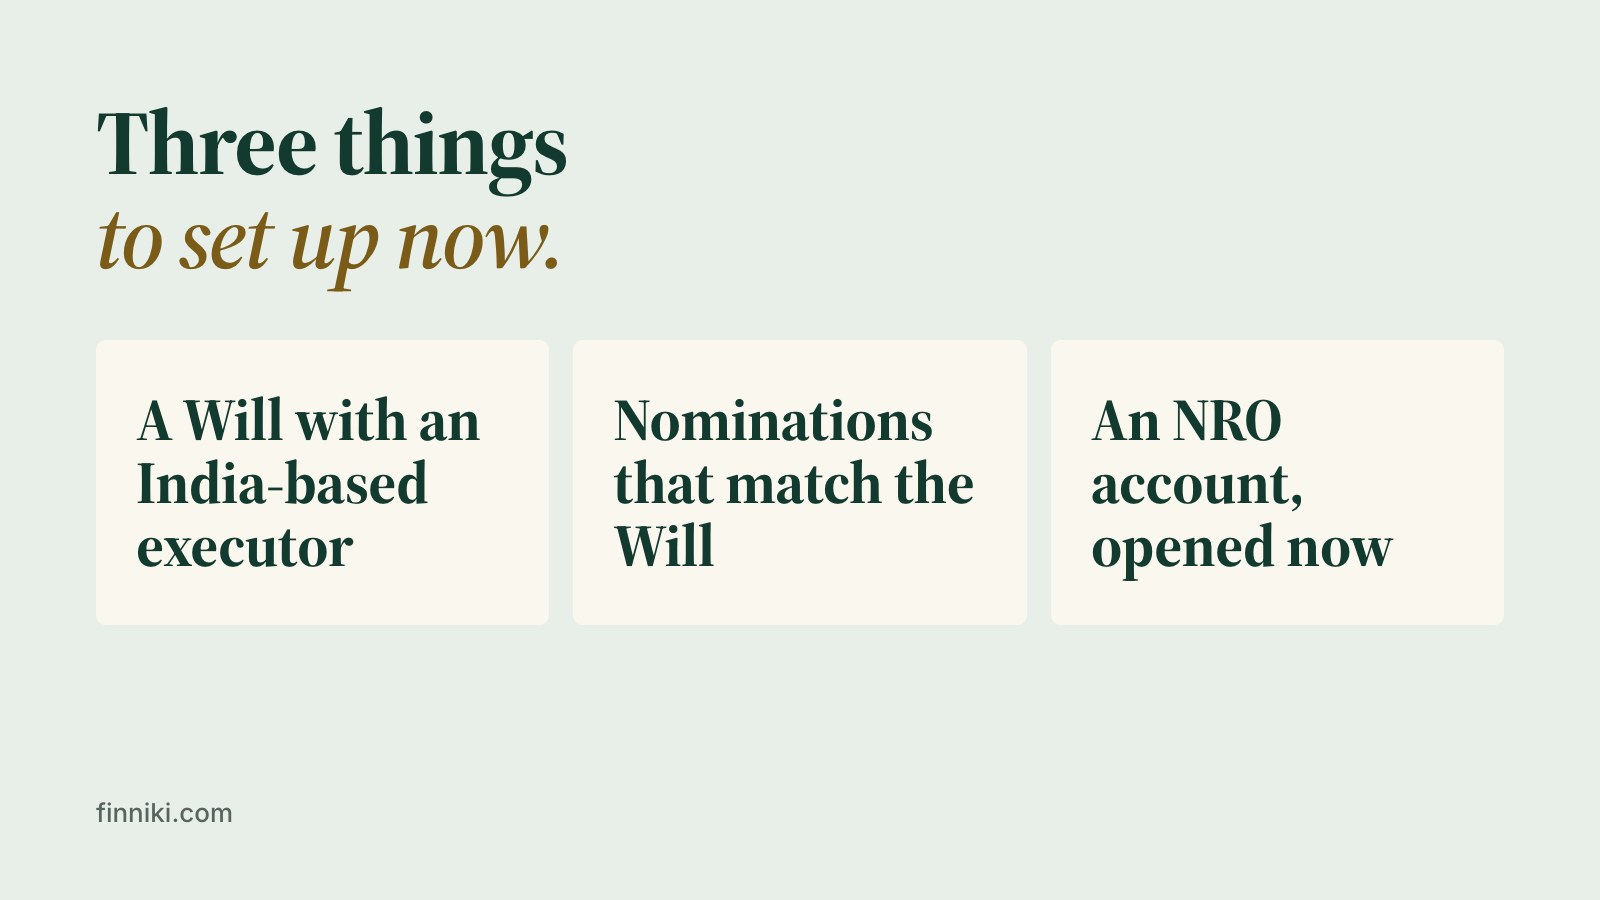
Quick answer: When your children live abroad, a Will alone is not an estate plan. You need five things: a Will with an India-based executor, a trust where the family or the assets are complex, nominations that match the Will, an NRO account your child opens now, and enough liquid assets that nobody has to sell a flat from overseas. Inheritance is tax-free in India, but when your child sells, capital gains are worked out from your original purchase price, and they can move only USD 1 million a year out of India. Plan it early with cross-border legal, tax and financial advice.
Updated October 2026. Probate is no longer compulsory anywhere in India: the Repealing and Amending Act 2025 removed section 213 of the Indian Succession Act from 20 December 2025. Bank accounts can now carry up to four nominees (from 1 November 2025), and the US estate tax exemption is US$15 million per person from 2026.
 Watch the episode: How parents can transfer assets to NRI children
Why is estate planning harder when your children live abroad?
Because the standard playbook assumes your heirs live down the road. Families with a Will and nominations still see children fighting paperwork from Toronto, property tied up for two years, and an inheritance that was "tax-free" turn into a large tax bill the moment it is sold. Indian banks, registrars and courts expect someone to turn up in person, repeatedly. A child with a job and a family abroad cannot. The fix is to build the plan around that fact, while you are alive and calm, not in the middle of grief.
Is a Will enough for NRI families?
No. A Will says who should receive your assets; it does not move them. Take Mr and Mrs Sharma (not their real names) in Pune, whose son Arjun lives in Toronto. Their Will left everything to Arjun. When Mr Sharma died, Arjun found that someone still had to visit the banks, deal with the property registrar and follow up on paperwork, in India, in person. What should have been simple took two years.
The Will is the map; you also need a driver. That is your executor, the person who carries out the Will. If your children live abroad, choose an executor who lives in India: a trusted relative, a friend or a family lawyer, someone who can actually show up.
Should NRI families set up a trust?
Often, yes, if your assets or your wishes are complex. A Will only takes effect after death; a trust can work during your lifetime and after it, with more control and fewer delays.
Take Rajesh (not his real name) in Hyderabad: three properties, a share portfolio and large fixed deposits. His daughter Naira is in Singapore and his son Aarav in London. He wants Naira to get the properties and Aarav the investments, but only after his wife is provided for, for life. A Will can attempt this; a trust carries it out cleanly, with little room for dispute.
A trust also keeps those assets away from probate, the court process that confirms a Will. Probate is no longer compulsory anywhere in India since December 2025, but banks and registrars can still ask for it or for a succession certificate, and a contested Will still ends up in court for months or years. Assets held in a trust do not pass under the Will at all.
The third reason is foreign tax. Depending on your family's citizenship and residence, your children's country may tax what they inherit, or later tax it again when it passes to your grandchildren. US federal estate tax and UK inheritance tax both reach 40% above their thresholds. A trust set up correctly and in advance can reduce that exposure; one set up after the fact usually cannot. As with the executor, choose an India-based trustee: the assets and the work are here.
Do nominations override a Will in India?
No. A nominee is, in most cases, a custodian, not the owner. The bank or fund pays the nominee, but your legal heirs under your Will or personal law keep their rights. The Supreme Court confirmed this for shares in 2023. Life insurance is the main exception: when the nominee is a spouse, child or parent, they generally take the money as their own.
Nominations matter most when they are missing. Without one, your NRI child may need a succession certificate, affidavits or a court order just to reach money that was always meant for them, which can take over a year.
The common gap: you named your spouse decades ago, when the children were minors, and never updated it. Or the form was never filled in. Spend an afternoon on it:
- List every bank account, fixed deposit, mutual fund, demat account and insurance policy.
- Add or update nominees. Banks now allow up to four nominees per account, with a share for each.
- Make sure every nomination matches your Will. If they point in different directions, the nominee collects and the other heirs can contest it.
Why does your NRI child need an NRO account before you die?
Because inherited money needs a home in India first. In practice, banks pay an NRI heir's inheritance into an NRO (Non-Resident Ordinary) account, the account NRIs use for money from India such as rent, investment proceeds and inheritance. From there your child can reinvest it or send it abroad.
Without one, everything stalls: the Will is valid, the nominations are right, and the money still has nowhere to go. Most major Indian banks let NRIs open an NRO account from abroad. Ask your child to open it now, while things are calm, not when a parent is in hospital.
Is it better to leave property or financial assets to NRI children?
A mix, with more liquid assets than most Indian parents hold. For a child abroad, an inherited flat is often more work than a gift. Your child in Dubai inherits a flat in Chennai. To sell it, they either fly in for the registration or sign a power of attorney abroad, notarised and apostilled (or attested at an Indian mission where apostille is not available) and then stamped in India. Finding a buyer takes time, and a seller who needs to sell from abroad gets a lower price. Meanwhile someone has to pay maintenance, manage the tenant, fix the roof and answer the property-tax notice.
Mutual funds, fixed deposits and listed shares move with standard paperwork, largely online, without a flight. You do not need to sell everything. As you get older, gradually shift a share of your wealth from property into liquid financial assets, so your children inherit options, not obligations.
Is inheritance taxable in India?
No, not when it is received. India has no inheritance tax. But once the inherited asset earns income, such as rent, interest or dividends, that income is taxable. And when your child sells it, capital gains tax applies, on a cost going back to what you originally paid, not the value on the day they inherited.
Say you bought a flat in 2002 for ₹20 lakh and it is worth ₹1.2 crore today. Your child inherits and sells it. The taxable gain is ₹1.2 crore minus ₹20 lakh: ₹1 crore. Your years of ownership count towards theirs, so it is a long-term gain. For an NRI seller, that is taxed at 12.5% without indexation: ₹12.5 lakh, or about ₹14 to 15 lakh once surcharge and cess are added on a gain of this size. The buyer will also deduct tax at source on the full sale price unless your child gets a lower-deduction certificate before the sale. Reinvesting in a home in India can reduce the tax.
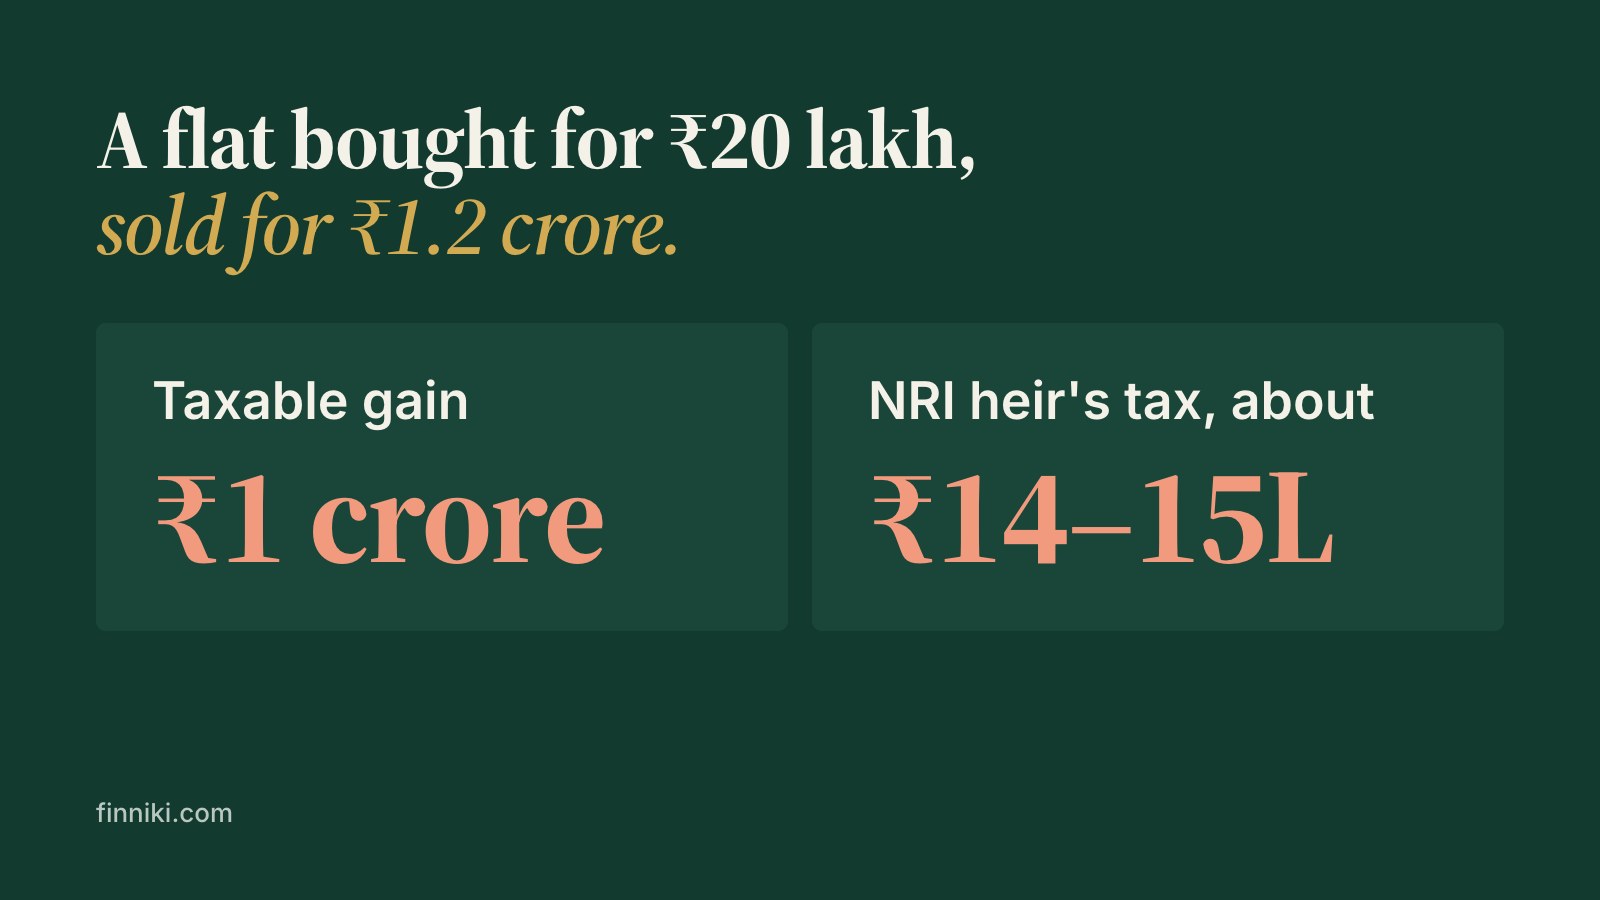
Nothing about this is unfair: the gain built up over decades and nobody paid tax on it. The problem is when it lands as a surprise. Do the maths before the sale, not after.
Will your child pay tax abroad on an Indian inheritance?
It depends entirely on the country, and on your citizenship as well as theirs:
- US: if you are an Indian resident and not a US citizen or green card holder, your US-citizen child generally owes no US tax on inheriting your Indian assets. They must still report a large foreign inheritance (over US$100,000) to the IRS. But if you are a US citizen or green card holder, your worldwide estate, including the flat in Pune, can fall under US estate tax, above the US$15 million exemption.
- UK: inheritance tax at 40% applies above a tax-free band, and since April 2025 it turns on long-term UK residence rather than domicile.
- Canada and Australia have no inheritance tax as such, but their own rules on capital gains and reporting.
Every country is different, and the wrong assumption here can cost crores. Get it checked for your family.
How much inherited money can an NRI take out of India?
Up to USD 1 million per financial year from an NRO account, which covers inheritance, after tax. That sounds a lot until you add a flat in Mumbai, an office in Bengaluru and a share portfolio: then your child is running a multi-year repatriation plan from abroad, and amounts above the limit need RBI approval. See how NRI repatriation works.
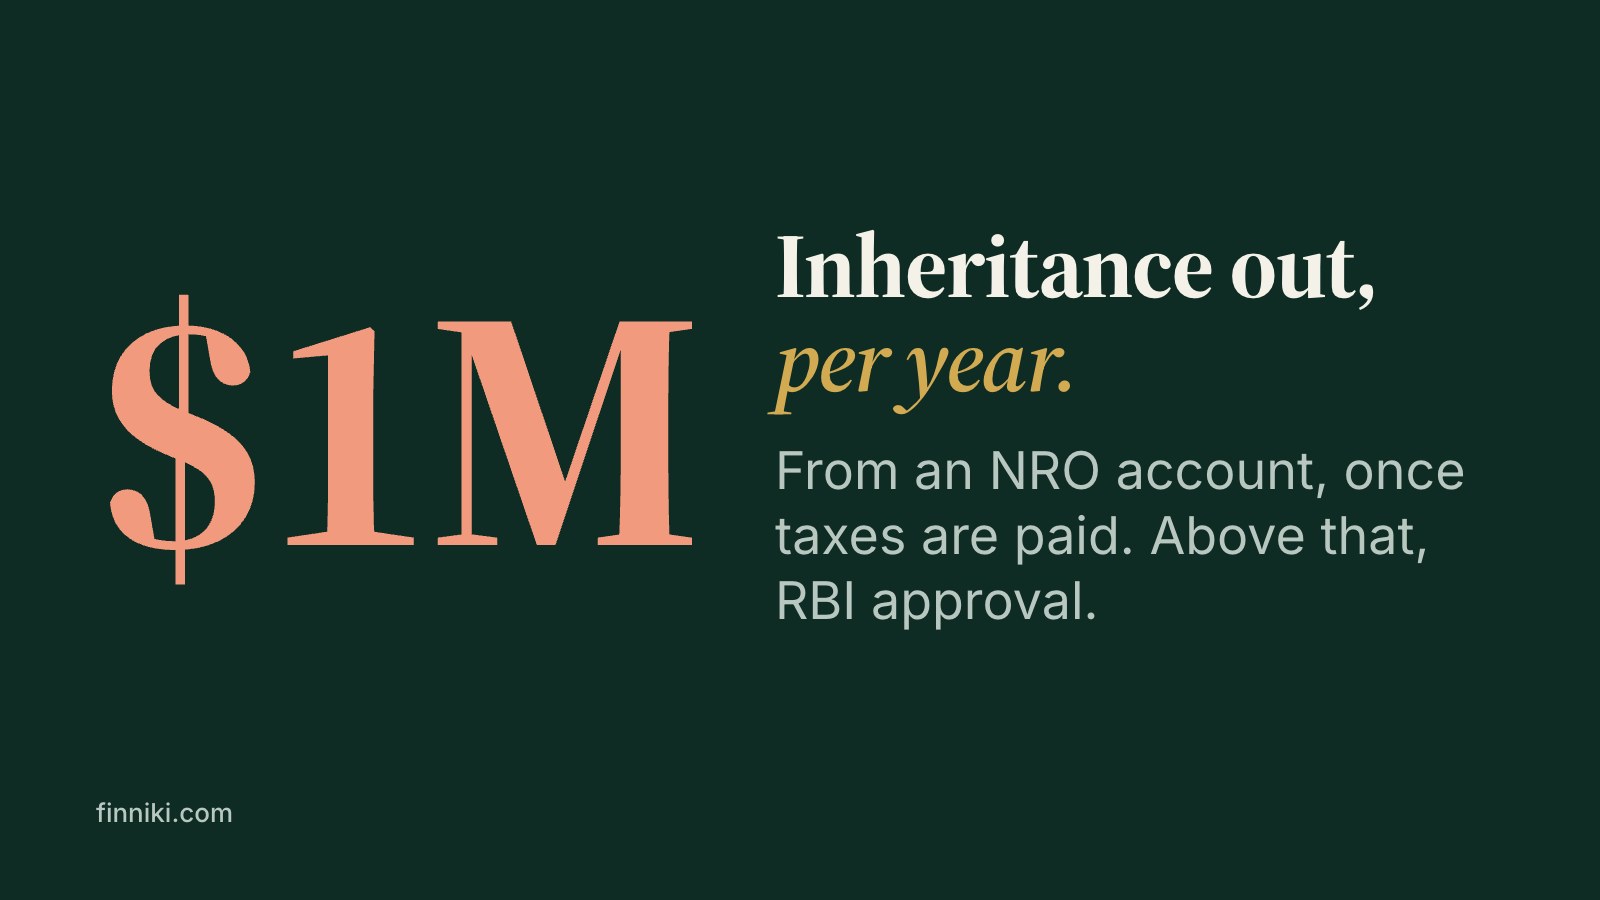
Giving while you are alive has its own cap: a resident Indian can send up to USD 250,000 per financial year abroad under the Liberalised Remittance Scheme, so moving wealth to a child gradually is a year-by-year plan.
Does a DTAA stop your child being taxed twice on an inheritance?
It helps, but not automatically. India's Double Taxation Avoidance Agreements (DTAAs) stop the same income being taxed in full by two countries. Say your child in the UK sells an inherited Indian property: India taxes the capital gain first, and when your child reports the same gain in the UK, they can claim a credit for the Indian tax, which reduces or removes the UK tax.
But your child has to know to claim it, and claim it in the right form in their country of residence. Miss that and they can pay tax twice on the same money. The rules differ by country and type of income, so a cousin in Australia and a sibling in Canada can end up with different answers on the same inheritance.
Which professionals do NRI families need?
Three skills, from one adviser or several:
- An international estate planning specialist, who understands how Indian structures work in your child's country. A gift that is fine in India can trigger a US reporting requirement; a trust that works under Indian law can create a UK tax charge.
- A Chartered Accountant with cross-border experience, who maps Indian tax, foreign tax and treaty relief together.
- A financial adviser in India, who manages your portfolio with transfer in mind: growing it, building liquidity and gradually shifting the asset mix.
Your estate planning checklist
- Start now, years before you need it. Families who struggle all say the same thing: "we thought we had more time".
- Shift towards liquidity. If most of your wealth is in property, your children are inheriting work.
- Organise your documents and tell your children where they are. Substantial assets go unclaimed because nobody knew they existed.
- Review the plan every year. A Will written when your child was on a work visa can have gaps once they take foreign citizenship.
- Talk to your children. If that feels too big, at least make sure someone knows the plan exists and where to find it.
FAQs
Is inheritance taxable in India?
No. Receiving an inheritance is not taxed, but income from it is, and capital gains tax applies when it is sold, on the original owner's cost.
Is probate mandatory in India?
No longer. Section 213 of the Indian Succession Act, which required probate for some Wills in Mumbai, Chennai and Kolkata, was omitted from 20 December 2025, though banks and registrars may still ask for it.
Can an NRI be a nominee?
Yes. You can name an NRI child as nominee on bank accounts, mutual funds, demat accounts and insurance, and banks now allow up to four nominees per account.
Does a nominee become the owner?
Usually not. A nominee receives the asset on behalf of the legal heirs, except life insurance nominees who are a spouse, child or parent.
How much inherited money can an NRI send abroad?
Up to USD 1 million per financial year from an NRO account, after tax; more needs RBI approval.
Does my NRI child pay US tax on an Indian inheritance?
Generally not, if the parent is not a US citizen or green card holder, but inheritances over US$100,000 from abroad must be reported to the IRS.
Who should be the executor if my children live abroad?
Someone who lives in India and can appear in person: a trusted relative, a friend or a family lawyer.
How is capital gains tax calculated on inherited property?
On the sale price minus what the original owner paid, and the original owner's holding period counts towards the heir's.
Plan it while there is time
The families who get this right started early, got the right advisers and told their children what was in place. If you are a parent with children abroad, or an NRI with parents in India, book a session to map your family's plan, or find more explainers on FinNiki videos.
General information, not advice for your situation. Rules change; check your own numbers with a CA before you act.